A hail claim example is most useful when it shows what actually happens after a storm: a homeowner notices damage, documents the property, files promptly, meets the adjuster, and gets a clear repair scope. The goal is not to inflate a claim. It is to make sure legitimate storm damage is seen, documented, and addressed before small roofing problems turn into leaks, rot, or interior repairs.
For Central New York homeowners, that process can feel stressful. Hail is often followed by high winds and heavy rain, which can leave behind damage that is not obvious from the ground. A professional roof inspection can help separate fresh storm damage from normal wear and explain what repairs may be needed.
A Realistic Hail Claim Example
Imagine a homeowner in the Syracuse area hears a sharp hailstorm hit overnight. The next morning, they find dents in a metal downspout, pockmarks on a few window screens, and several dark spots on asphalt shingles visible from the driveway. There is no active leak inside the home, but the roof is about 12 years old.
The homeowner takes date-stamped photos of the yard, dented gutter components, screens, and any visible roof marks without climbing onto the roof. They also save a local weather alert showing the date of the storm. That same day, they call their insurance carrier to report a possible hail loss and schedule a roof inspection with a qualified local contractor.
During the inspection, the contractor finds hail impact marks across multiple roof slopes. The impacts have displaced shingle granules and bruised the asphalt mat beneath them. The inspector also finds dents on soft metal vents and additional gutter damage. Those collateral impacts matter because they can support the conclusion that the roof was exposed to the same hail event.
The insurance company assigns an adjuster. At the adjustment appointment, the contractor and homeowner review the affected areas together with the adjuster. The adjuster agrees that the roof has storm-related hail damage and prepares an estimate for replacing the damaged roofing system, certain metal accessories, and affected gutters. The homeowner pays the policy deductible, and covered work proceeds according to the insurer’s approved scope.
That is a straightforward hail claim example, but real claims can vary. An adjuster may find only limited damage that supports repair rather than replacement. A policy may have special deductibles, actual cash value terms, or exclusions that change the final payment. Documentation and a careful inspection cannot change policy language, but they can help ensure the condition of the property is accurately presented.
What Makes a Hail Claim Stronger
A strong claim is built on facts, not pressure. Hail damage can be difficult to identify because a shingle may look mostly intact while the impact has weakened its protective surface. The best evidence connects the storm date, visible collateral damage, roof findings, and repair recommendation.
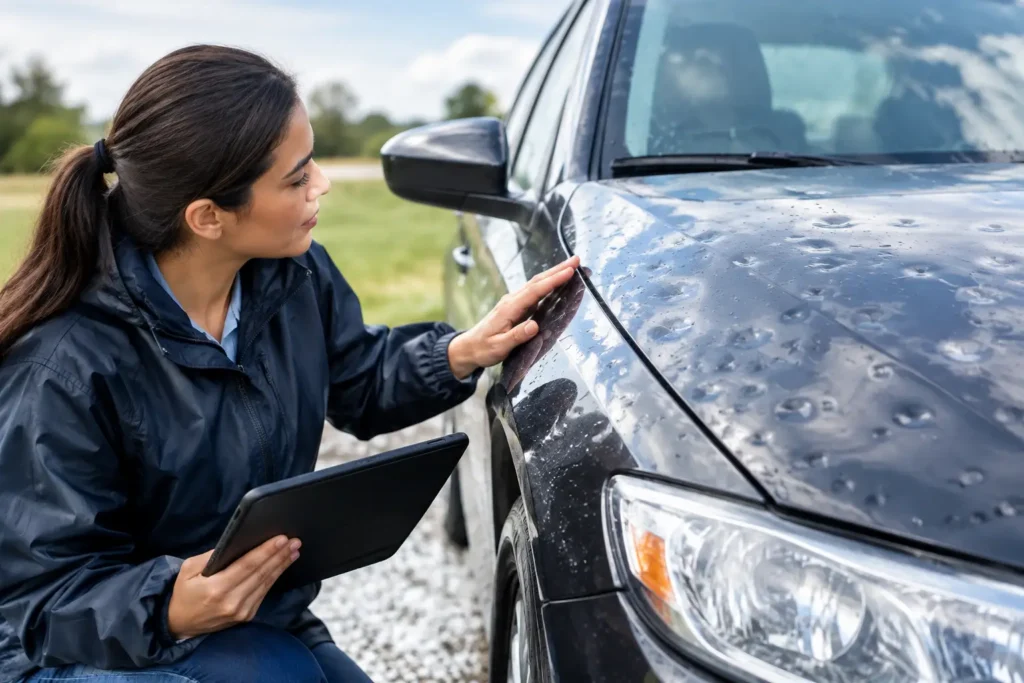
Start with photos from the ground as soon as conditions are safe. Photograph hailstones if they are still present, along with dents on downspouts, flashing, vents, outdoor furniture, siding, screens, or air-conditioning equipment. Wide photos establish location, while close-ups show the detail of a dent or impact mark.
Next, make a simple written record. Note the date and approximate time of the storm, what you heard or observed, and any changes you notice afterward. If water appears in the attic or on a ceiling, photograph it immediately and take reasonable steps to prevent further damage. Insurance policies commonly require homeowners to protect the property from additional loss, so temporary measures such as a tarp may be appropriate when there is an active opening.
A professional inspection adds another layer of clarity. A roofing contractor can examine shingles, ridge caps, valleys, vents, flashing, gutters, and the attic for signs of impact or water intrusion. They should explain their findings plainly and provide photos where possible. Be cautious with anyone who promises approval before reviewing the roof and the policy details. No contractor can guarantee what an insurer will cover.
The Difference Between Hail Damage and an Old Roof
Age alone does not prevent a hail claim, but it can affect how an insurer values the loss. A 15-year-old roof may have normal granule loss, weathering, thermal cracking, nail pops, or worn sealant before a storm ever arrives. Those conditions are not necessarily hail damage.
Hail damage usually has a more distinct impact pattern. On asphalt shingles, a qualified inspector may look for circular or irregular areas where granules have been knocked away, exposed asphalt, fractured or bruised matting, and fresh impacts in several locations. On metal components, hail often leaves dents that are easier to see. The pattern should make sense across the roof and other exposed surfaces.
This distinction matters because an honest inspection protects the homeowner as well. Filing a claim for ordinary aging when no storm damage is present can lead to frustration and wasted time. On the other hand, assuming an older roof cannot have a valid storm claim can leave legitimate damage unaddressed until it causes leaks.
What to Expect After You File
After opening a claim, you will receive a claim number and instructions from the insurance company. Keep that number with your photos, inspection notes, and all communication related to the loss. Ask when an adjuster will inspect the property and whether the insurer needs any documents before the appointment.
If possible, be present for the inspection. You can point out where you observed damage and ask the adjuster to explain what they are documenting. Having your roofing contractor present can also be helpful when there are technical questions about shingle damage, flashing, ventilation components, or the work required to restore the roof properly.
When the estimate arrives, read the scope carefully. Look at the listed materials, roof sections, quantities, waste allowance, flashing, vents, gutters, and other components that may have been damaged. If the scope does not appear to include work needed to complete a proper repair, ask questions before construction begins. In some cases, additional damage becomes visible only after old materials are removed. That situation may require documentation and a supplemental review.
Do not confuse an insurance estimate with a construction contract. The estimate describes what the carrier currently recognizes as covered damage under the policy. Your contractor should still provide a clear written proposal explaining the planned work, materials, timing, and any homeowner responsibility beyond the insurance payment.
Common Mistakes That Can Complicate a Claim
The most common mistake is waiting too long. If a homeowner delays reporting damage for months, it can become harder to connect the condition to a specific storm. Prompt reporting also gives you a better chance to catch small roof issues before the next round of rain, snow, and freeze-thaw cycles.
Another mistake is climbing onto a steep or wet roof for close-up photos. Hail damage is not worth a fall. Take safe ground-level photos, then let a trained roofing professional inspect the roof.
Homeowners can also run into trouble by relying on verbal promises. Keep written estimates, inspection findings, invoices, and messages. If an adjuster, contractor, or insurer representative explains a decision, ask for the important details in writing.
Finally, do not sign an assignment of benefits or a contract you do not understand just because someone says your claim will be handled for you. A reputable contractor should be willing to explain the paperwork, answer direct questions, and give you time to make an informed decision.
When to Call a Roofing Professional
Call for an inspection after a known hailstorm if you see dents on metal fixtures, loose or missing shingles, granules collecting in gutters, water spots indoors, or debris around the home. You should also call if nearby homes are being inspected after the same storm. Damage can be uneven, and a roof may be affected even when it is not obvious from the street.
Alpha Omega Roofing LLC helps homeowners understand storm-related roof conditions with straightforward inspections and clear repair or replacement recommendations. The right next step is simple: document what you can safely see, report the loss promptly if damage is suspected, and get a professional opinion before a minor issue has the chance to become a major repair.